Understand how partnership distributions, taxable income, and tax basis affect real estate investors.
One of the most common surprises in real estate syndications is also one of the most important: the amount of cash an investor receives is not necessarily the amount of income the investor pays tax on.
An investor may receive a healthy cash distribution and report little or no current taxable income. Another investor may receive no cash at all and still owe tax because the partnership allocated taxable income on Schedule K-1. Understanding that difference is essential for underwriting returns, managing investor expectations, and avoiding year-end tax surprises.
Quick answer
Cash distributions from real estate partnerships are generally not taxable when received. Instead, investors are typically taxed on their share of partnership income reported on Schedule K-1, regardless of whether they receive a cash distribution.
Cash distributions generally reduce an investor's tax basis in the partnership. However, distributions that exceed the investor's adjusted tax basis may result in taxable gain.
Simply put: Your K-1 reports your share of the partnership's taxable income or loss, while a distribution represents the cash you actually receive.
In this article, we'll explain why cash distributions and taxable income don't always align in real estate syndications, how partnership tax rules affect investors, and what questions to ask before investing.
Keep in mind that tax implications vary based on individual circumstances, including your state, other income, filing status, and the investment's performance. Consult your CPA to understand how these rules apply to your specific situation.
Why do investors confuse distributions with income?
In everyday language, “income” often means cash received. If an investor receives a $10,000 distribution, it feels natural to assume the investor has $10,000 of taxable income.
Partnership tax rules do not work that way.
A real estate syndication is often structured as an LLC taxed as a partnership. In that setup, the partnership typically doesn’t pay federal income tax itself. Instead, it “passes through” income and deductions to investors, who report those items on their own returns.
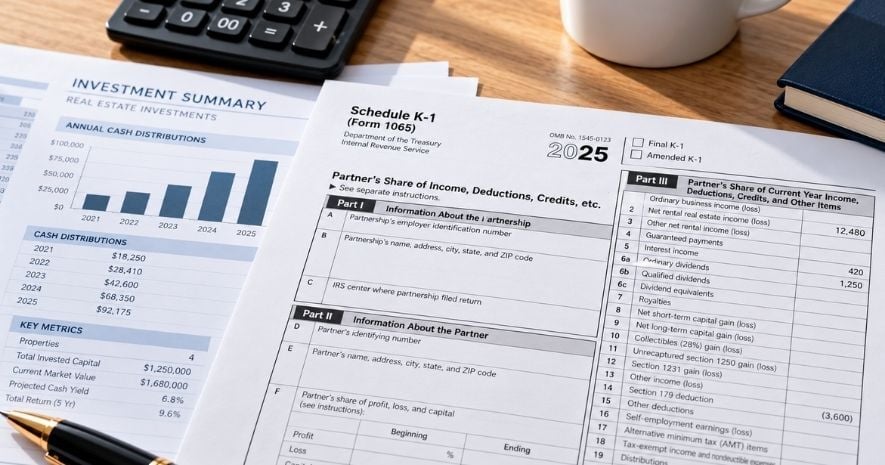
That means the partnership computes its taxable income, deductions, gains, losses, and credits, and then reports each partner’s share on Schedule K-1. The investor reports those K-1 items on the investor’s own tax return.
K-1 Income vs. Distributions: What's the Difference?
A simple way to think about it is:
|
Concept |
What it means |
Does it create current taxable income? |
Effect on outside basis |
|
K-1 taxable income |
Your share of the partnership’s taxable income (it can be rental income, interest, capital gain, etc.) |
Yes |
Usually increases your tax basis |
|
K-1 loss |
Your share of deductions/losses (often from depreciation) |
Maybe—many investors can’t use it right away |
Usually decreases your tax basis |
|
Cash distribution |
Cash the partnership actually sends you |
Usually not taxable when received |
Usually reduces your tax basis |
|
Debt/liability decrease |
Your share of the partnership’s debt goes down (common after principal paydown or a refinance) |
Can be treated like a “phantom” cash distribution |
Can reduce your basis and sometimes create taxable gain |
The key point: a distributive share is not the same thing as a distribution. A partner may be taxed on partnership income even if the partnership does not distribute cash or even if the income could not have been distributed.
How does partnership pass-through income work?
The partnership totals up its taxable income and deductions for the year, then reports your share on a Schedule K-1. That K-1 can include different types of items—some are taxed like ordinary income, others like capital gain, and some are deductions.
That means a K-1 may include items such as:
- Rental real estate income or loss;
- Interest income;
- Dividend income;
- Short-term or long-term capital gain;
- Section 1231 gain or loss;
- Charitable contributions;
- Credits; and
- Other separately stated items.
How these items are split among investors is determined by the operating agreement, subject to tax rules that generally require allocations to reflect the economics of the deal.
The entity's tax structure can influence how income, losses, distributions, and debt are treated. Learn more about the differences between Schedule E, partnerships, and S corporations for real estate investors.
Why might an investor owe tax without receiving cash?
This is sometimes called phantom income. It happens when the investor is allocated taxable income, but the partnership does not distribute enough cash to cover the tax.
In real estate syndications, that can occur because cash may be used for:
- Debt service, including principal payments;
- Capital improvements;
- Leasing costs;
- Replacement reserves;
- Operating reserves;
- Insurance, taxes, or lender-required escrows;
- Tenant improvements;
- Deferred maintenance; or
- Reinvestment into the property.
Some of those cash outflows may not produce an immediate tax deduction. For example, principal payments reduce debt but generally do not reduce taxable income the same way interest expense does. Capital improvements may need to be capitalized and depreciated over time rather than deducted immediately.
The result: taxable income can exist even when distributable cash is limited.
Case Study 1: Taxable income without cash distributions
Let’s translate the concept into numbers.
Facts
Assume:
- A real estate partnership has $500,000 of taxable income for the year.
- An investor owns 10% of the partnership.
- The investor receives no cash distribution because the partnership retains cash for reserves, debt service, and capital improvements.
- The investor’s beginning outside basis is $100,000.
- The investor’s combined federal and state marginal tax rate is assumed to be 37% for illustration.
- No debt allocation changes are assumed.
Tax result
The investor’s distributive share of taxable income is:
$500,000 × 10% = $50,000
The investor may owe tax on that income even though no cash was distributed:
$50,000 × 37% = $18,500 estimated tax cost
Basis result
The taxable income generally increases the investor’s outside basis:
|
Item |
Amount |
|
Beginning outside basis |
$100,000 |
|
Add: allocated taxable income |
50,000 |
|
Less: cash distributions |
— |
|
Ending outside basis |
$150,000 |
Planning takeaway
The investor has $50,000 of K-1 income but $0 of cash distributions. This is why investors should ask whether the sponsor projects taxable income in years when cash may be retained.
Can an investor receive cash without taxable income?
Yes. This is common in real estate investments, especially in earlier years when depreciation, cost segregation, interest expense, and other deductions may reduce taxable income.
A cash distribution is not automatically taxable income. In general, a current cash distribution is taxable only if the cash (including certain “deemed cash” from debt changes) is more than your tax basis in the investment.
There are important exceptions and special rules, but most investors can remember this practical version: cash distributions are often a return of your invested capital for tax purposes until you “run out” of basis.
What is outside basis, and why does it matter?
Tax basis (often called “outside basis”) is a running total that helps determine how distributions and losses are treated on your tax return. It matters because it affects:
- Whether cash distributions are taxable;
- Whether losses are currently deductible;
- Gain or loss on sale of the partnership interest;
- Tax consequences of refinancing or liability shifts;
- Suspended losses; and
- Exit planning.
At a high level, outside basis generally starts with the investor’s capital contribution, then changes over time.
Outside basis generally increases for:
- Additional capital contributions;
- Allocated taxable income and gains;
- Certain tax-exempt income; and
- Increases in the investor’s share of partnership liabilities.
Outside basis generally decreases for:
- Cash distributions;
- Certain noncash property distributions;
- Allocated losses and deductions;
- Certain nondeductible expenses; and
- Decreases in the investor’s share of partnership liabilities.
A distribution that exceeds your tax basis can trigger taxable gain.
Why do debt and liability allocations require special care?
Real estate partnerships often use debt. Debt can increase outside basis, but changes in debt allocations can also create unexpected tax consequences.
When partnership debt changes, your share of that debt can change too. In tax terms, a decrease in your share of debt can be treated like you received cash—even if you didn’t.
That matters because a deemed cash distribution can trigger gain if it exceeds the investor’s outside basis.
Why this is hard to “eyeball”
Liability allocations are not always based simply on ownership percentages.
- Recourse liabilities are generally allocated to partners who bear the economic risk of loss, including through guarantees or other payment obligations.
- Nonrecourse liabilities are generally allocated under a regulatory framework that includes partnership minimum gain, Section 704(c) minimum gain, and excess nonrecourse liabilities.
- A guarantee of otherwise nonrecourse debt may shift liability basis to the guarantor, depending on the facts and regulatory rules.
For investors, the most important point is this: a refinance, principal paydown, or guarantee structure can affect taxes even if no cash is paid directly to you.
How do passive activity loss rules affect syndication investors?
Many real estate syndication investors are passive investors. Even if a K-1 reports a loss, the investor may not be able to use that loss immediately.
Under the passive loss rules, many syndication losses are “passive,” which often means you can’t use them today to offset wages or business income. They may carry forward until you have passive income or you sell your entire interest.
Rental activities are generally passive unless an exception applies, and limited partnership interests are generally not treated as materially participated in except as provided by regulations.
What this means in practice
A passive investor’s real estate syndication losses may:
- Offset passive income from other activities;
- Be suspended if passive losses exceed passive income;
- Carry forward indefinitely under IRC Section 469(b);
- Potentially be released when the investor disposes of the entire activity in a fully taxable transaction to an unrelated party under IRC Section 469(g); and
- Remain subject to other limitations, including basis and at-risk rules.
This is why a projected K-1 loss does not always mean an investor will receive a current tax benefit.
What should investors ask before investing?
Investors should conduct due diligence on both the economics and the tax profile of the deal.
Key investor questions
- What are the projected annual cash distributions?
- What are the projected annual K-1 taxable income or loss amounts?
- Are tax projections prepared on a federal-only basis or do they include state estimates?
- Does the model assume cost segregation or bonus depreciation?
- When are depreciation benefits expected to taper off?
- Could the deal generate taxable income before a sale or refinance?
- Does the operating agreement provide for tax distributions?
- Are tax distributions mandatory, discretionary, or subject to available cash and lender restrictions?
- How are liabilities allocated among partners?
- Could refinancing or debt paydown reduce outside basis?
- Will losses likely be passive and potentially suspended?
- Does the sponsor provide draft K-1 estimates before final K-1 delivery?
Two key tax questions every investor should ask
- Will you show investors a year-by-year estimate of (1) cash distributions and (2) K-1 taxable income/loss? Those are different schedules.
- If there’s taxable income but limited cash, how will investors pay the tax? (For example, is there a tax distribution policy?)
What are tax distributions?
A tax distribution is a distribution intended to help partners pay taxes on allocated taxable income.
Tax distributions are not automatic unless the operating agreement requires them. Even when an agreement includes tax distribution language, the provision may be limited by:
- Available cash;
- Lender covenants;
- Reserve requirements;
- Preferred return waterfalls;
- Manager discretion;
- Clawback or true-up provisions;
- Different tax rates among investors; and
- Whether income is allocated disproportionately.
A sponsor may say the deal “plans for tax distributions,” but investors should confirm what that means legally and economically.
Practical diligence checklist for sponsors and investors
Use this checklist before issuing projections, reviewing an offering, or preparing for year-end tax reporting.
Partnership structure and reporting
- Confirm the entity is taxed as a partnership for federal income tax purposes.
- Review the operating agreement’s allocation provisions.
- Confirm whether allocations are intended to comply with substantial economic effect rules.
- Identify separately stated items that may flow through on Schedule K-1.
- Confirm whether K-1 items may include ordinary income, rental income, capital gain, Section 1231 gain, credits, or other items.
Cash distribution planning
- Separate projected cash distributions from projected taxable income.
- Review distribution waterfalls and preferred return provisions.
- Identify whether distributions are current, refinancing-related, sale-related, or liquidating.
- Confirm whether distributions may exceed outside basis for some investors.
- Review whether tax distributions are required or discretionary.
Basis and liability planning
- Track each investor’s outside basis annually.
- Model the effect of income, losses, distributions, and debt allocations.
- Identify recourse and nonrecourse liabilities.
- Review guarantees and reimbursement rights.
- Model refinances, principal paydowns, and debt modifications.
- Evaluate whether liability reductions could create deemed cash distributions.
Passive activity and investor-specific limits
-
Determine whether projected losses are passive to the investor.
-
Ask whether the investor has passive income from other sources.
-
Consider whether losses may be suspended under IRC Section 469.
-
Consider basis, at-risk, and passive loss limitations separately.
-
Avoid promising that tax losses will be currently usable by all investors.
State and compliance items
- Identify all state filing obligations.
- Determine whether composite returns or withholding apply.
- Review state depreciation conformity.
- Consider pass-through entity tax elections.
- Provide investors with estimated K-1 timing.
- Communicate tax projection updates when business plans change.
3 key planning takeaways
-
Cash flow and taxable income are different measurements. Cash distributions show what the investor received. K-1 income shows what the investor must report for tax purposes. The two often differ.
-
Basis is the bridge between cash and taxability. Distributions are generally tax-free only to the extent of outside basis. Once distributions or deemed distributions exceed basis, taxable gain may result.
-
Tax projections should be updated throughout the deal. Refinancing, debt paydowns, capital improvements, depreciation changes, and operating results can all change the tax profile. Sponsors and investors should revisit projections annually, not only at acquisition.
Conclusion
Distributions are not income. They are cash movements between a partnership and its partners. Taxable income is determined under the partnership tax rules and reported on Schedule K-1.
For real estate syndication investors, the practical lesson is clear: do not evaluate a deal only by its projected cash-on-cash return, IRR, or equity multiple. Ask how taxable income, depreciation, debt allocations, basis, passive loss limitations, and state taxes are expected to behave over the life of the investment.
For sponsors, the planning lesson is equally important: communicate cash projections and tax projections separately. Investors are better served when they understand not just how much cash they may receive, but also when taxable income may arise, whether losses may be suspended, and whether tax distributions are available.
The best tax outcome is rarely accidental. It comes from modeling the economics, tracking basis, understanding the operating agreement, and revisiting tax projections as the business plan changes. Trout CPA's real estate accounting and tax professionals help investors and developers navigate these complexities and plan for the tax implications of their investments.
Technical note (for readers who want the “why” behind the rules)
Most real estate syndications are taxed as partnerships. At a high level:
- Partnerships generally don’t pay federal income tax at the entity level; partners are taxed on their share of income.
- Partnership items flow through to partners and keep their character on the K-1.
- A partner can be taxed on allocated income even if nothing is distributed.
- Current cash distributions are generally tax-free until they exceed outside basis; distributions reduce basis.
- A decrease in a partner’s share of partnership liabilities can be treated like a cash distribution and can create gain if basis is insufficient.
FAQs
Are partnership distributions taxable income?
Not automatically. A cash distribution from a partnership is generally taxable only to the extent the money distributed exceeds the partner’s outside basis under IRC Section 731(a)(1). Otherwise, it generally reduces outside basis under IRC Section 733.
Can I owe tax if I did not receive a distribution?
Yes. Partners are taxed on their distributive share of partnership income regardless of whether the income was actually distributed.
Does a partnership pay federal income tax?
Generally, no. Under IRC Section 701, a partnership is generally not subject to federal income tax at the entity level; instead, partners are taxed in their separate capacities. State, local, and special entity-level tax regimes may require separate analysis.
Can refinancing create taxable income?
A refinancing itself does not always create taxable income, but it can change liability allocations or produce distributions. A decrease in a partner’s share of partnership liabilities can be treated as a deemed cash distribution under IRC Section 752. If actual and deemed distributions exceed outside basis, gain may result.
Are passive losses from a syndication always currently deductible?
No. Under IRC Section 469, passive losses are generally deductible only against passive income and may be suspended if passive losses exceed passive income.